Showing posts with label Islamic Finance. Show all posts

Monday, April 7

Of Religion and Redemption: Evidence from Default on Islamic Loans

I think I am getting religion. Fascinating study

We compare default rates on conventional and Islamic loans using a comprehensive monthly dataset from Pakistan that follows more than 150,000 loans over the period 2006:04 to 2008:12. We find robust evidence that the default rate on Islamic loans is less than half the default rate on conventional loans. Islamic loans are less likely to default during Ramadan and in big cities if the share of votes to religious-political parties increases, suggesting that religion – either through individual piousness or network effects – may play a role in determining loan default.

Looks like a great idea to me, I wonder why banks aren't cottoning on to this fact :) :P

Monday, June 17

Islamic vs. conventional banking: Business model, efficiency and stability

This paper was quite an interesting one. I quote the abstract:

How different are Islamic banks from conventional banks? Does the recent crisis justify a closer look at the Sharia-compliant business model for banking? When comparing conventional and Islamic banks, controlling for time-variant country-fixed effects, we find few significant differences in business orientation. There is evidence however, that Islamic banks are less cost-effective, but have a higher intermediation ratio, higher asset quality and are better capitalized. We also find large cross-country variation in the differences between conventional and Islamic banks as well as across Islamic banks of different sizes. Furthermore, we find that Islamic banks are better capitalized, have higher asset quality and are less likely to disintermediate during crises. The better stock performance of listed Islamic banks during the recent crisis is also due to their higher capitalization and better asset quality.

Given the financial crisis, this new model has quite a lot of lessons for the modern Anglo Saxon world of banking. I've been keeping track of Islamic Finance for some time now and this has changed quite a lot since the early days.


Full-size image (26 K)

The profit sharing element has quite an interesting behaviour as they end up being better capitalised with lower loan losses. In other words, they become a sort of private equity type of firm. Interesting, I wonder if these lessons will be learned by the regulators? Or force bad performing loans to be converted into equity like the CoCo’s? Not for the banks but for the firms to which the banks have lent to?

Saturday, April 2

Gold Dinar for Islamic Countries

The Dinar has long since has had exotic and evocative images, starting from piles of dinar’s in the pots in Alladin’s cave to the very fact that its gold. Anyway, one Malaysian state has gone and launched the Gold Dinar and Silver Dirham as its currency, apparently in a bid to be more Arab than the Arabs. Besides the fact that the actual Arabs think these wannabe Arabs are clowns and look down upon them, but when you wrap these things in religion, then everything is all right, its a one large happy family and and and. So what are the chances that the OIC suddenly goes into a collective huddle and decides that all countries will suddenly adopt the Dinar and Dirham. Well, ummm, no, not according to this research.

I quote the research highlights:

► This study suggests the lack of broad linkages within the entire OIC. ► Given OIC’s diversity, the idea of a Gold Dinar for the entire OIC may be stillborn. ► There exists scope among some smaller clusters for potential monetary union. ► Bahrain/ Saudi, Qatar/ Kuwait of the GCC states show symmetrical supply shocks. ► Bahrain, Qatar, Saudi, UAE have same response of GDP and prices to supply shocks.

Give it some more time, guys, then it could potentially work. But the areas concerned are just too different. Still, the OIC has its work cut out for it if it wants to evolve this monetary system. Although why on earth would anybody take anything that the OIC says seriously is beyond me, that organisation is about as useful as a bladeless knife with no handle.

Saturday, June 5

Five things you need to know about: The global Muslim market

This was a fascinating article. I am a bit interested in Islamic Finance. It provides a fascinating alternative to the currently held normal rules of investing and financial behaviour. Although I have my serious doubts about the “practises” of pricing Islamic instruments, the concept is quite interesting. A Muslim Private Equity sector so to say. So from that perspective, I agree with what the author says:

1. The size of the prize.

The global Muslim community, the ‘Ummah’ is huge – nearly 1.8 billion people around the world. The majority of those people are in Asia, particularly South and East Asia. It’s also a very young demographic – 52 per cent are under 24 years old. Author Vali Nasr has described this as ‘the third one billion market’ after China and India. However it has been widely neglected and has massive economic potential.

There are actually very few products that you can pitch to this entire population. So that has to be very clear. I cant say anything about Islamic Shampoo’s but what I can talk about are financial products. So the products that one can think about in this area are travel insurance, pilgrimage loans of a sort, basic mortgages, project financing, letters of credit, etc.

2. Don’t believe stereotypes.

Modern Muslims are going through a major period of re-assessment of their relationships with religious structures, cultural assumptions, authority, consumption and technology. This can be quite confusing for observers. A move towards conservatism in dress, for example, does not imply a rejection of hi-tech lifestyle items. They are often highly technically literate but at the same time do not see accepting Western technology as a reason to accept ideas they see as wrong.

This is nothing new, from time immemorial, Muslims have constantly reassessed their relationship with religious structures and frameworks. This is one of the reasons why so many sects of Islam have come forth. Also, I am not sure what this western technology is. Is Japanese technology western technology? How about the tech developed by India? This is a bit of a weird statement. And ironically, the chap warns against stereotypes and then proposes 5 rules/statements for the global muslims.

3. Tokenism doesn’t work.

Stamping products as Halal or Shariah-compliant is not enough. In fact our research shows that despite all the investment in Shariah banking, finance is seen as the least trusted category. Muslim consumers are highly interested in the authenticity and provenance of brands and the companies behind them. Their trust is therefore difficult to win, but once achieved is likely to be deeper.

This is indeed problematical. We dont have that many people who are cognisant of all the intricacies of finance versus Sharia. Then you end up in the problem of different sects. So there is over-reliance on a very few number of people who judge the authenticity and provenance of brands. Does that work to endanger trust? Sometimes.

4. It’s an open market.

You don’t have to be Muslim to be Shariah. Only 10 per cent of Muslim consumers cite manufactured for Muslims only as an important attribute when selecting brands. Ethics and business practice are perceived as more important.

Fair point


5. Engage strongly, but carefully.

The Muslim community is very open to marketers who seek their custom, so long as they feel it is done sincerely and honestly. However they are also fiercely protective of their religion and its culture, and very unforgiving to marketers who make mistakes or are seen to be hypocritical in their standards. There are many cases of bad errors in packaging, promotion and business practice.

Well, this is a matter for faith. When somebody asks me about Islamic Finance, I tell them to think about organic food. Its the same thing, for want of a different flavour, people are willing to pay more in a premium. But if the food turns out to be inorganic, trust is diminished and the stuff wouldnt sell.

Monday, May 10

First Islamic exchange to launch in London in May

Interesting news. The first Islamic ETF to help firms raise money. I quote:

The first electronic trading platform allowing sharia-compliant companies to raise cash will launch in London in May, the venture capital firm behind the project told Reuters on Thursday.

The Sharia Ummah Securities Information Exchange (UMEX) is designed to provide a platform to companies with a capital value of at least 20 million pounds ($31 million) and looking to raise the equivalent of at least 20 percent of their market value.

Fascinating stuff, and no, there is no issue elsewhere with interest rates or anything. At least not that I can see. With 10 Islamic Enterprises and over 100 Sharia Compliant Securities on the secondary market through IPOs, this is a good start although I wonder about the liquidity and depth of the market. Is there indeed that much liquidity available on this? Secondly, if there are day traders active on the market, i would posit that that will make it speculation. Which is obviously a bit difficult challenging from a Sharia perspective as you cant make money out of money.

But still interesting to see how this works out and what the returns are. As an aside, I found it eye catching that they appointed a Hindu to run it :), good for them :)

Thursday, March 18

Competitive conditions in Islamic and conventional banking: A global perspective

Very interesting paper. Here’s the abstract:

I analyze the competitive conditions prevailing in Islamic and conventional global banking markets, and investigate the possible differences in profitability between these markets, using a sample of banks across 13 countries during 2000–2006. The results suggest that Islamic banks allocate a greater share of their assets to financing activities compared to conventional banks, and they are also better capitalized. Different computed measures of competition indicate that Islamic banking is less competitive compared to conventional banking. A second-stage analysis shows that profitability significantly increases with market power, but this does not warrant higher profitability levels for Islamic banks.

Now the higher capitalisation might well be due to the fact that regulators usually ask for a higher degree of capital from Islamic banks. But when you compare this result with this paper which i reviewed before, then one wonders if there is really that much of a difference?

Secondly, the author finds that the Islamic Banks are not really having higher returns for devoting their attention to the Islamic customer base. The author suggests that this is more due to future revenue expectations and the western banks are getting into this market because of the rise of religiosity and customer demand.

I am not getting a clear picture of the differences then, the products are in effect the same, the same institutions are in both areas, the pricing is basically the same, risks are different but that’s mainly because of higher capital regulatory requirements. Hmmm, a rose by any other name if a bit more expensive?

Sunday, November 29

Muslim women and micro loans

This causes me no end of frustration. I mean, it's tough enough to get the economic status of women up and running. And then you have these bloody medieval obscurantists who come and bollox it up. I quote:

Ramesh Bellamkonda heads BSS Microfinance, the worst hit of several microfinance institutions (MFIs) in Karnataka. He says BSS has provided microcredit for two years in Kolar, three-and-a-half in Mysore, and eight in Ramanagaram, enjoying excellent relations with its Muslim borrowers and virtually 100% repayment. Today, repayment is down to almost zero, because of non-repayment directives by the anjumans and their goons, who threaten and even assault BSS staff. Muslims constitute a substantial proportion of borrowers, so the anjuman directives can bankrupt entire MFIs, affecting other community borrowers too. Other Karnataka MFIs in several towns face the same problem, and have been obliged to halt lending to Muslims. It is a triumph for the most reactionary Muslims, and a tragedy for Muslim women denied empowerment through finance.

The anjumans say interest on loans is un-Islamic, and so borrowers need not repay, and no further microloans should be given to Muslims…….Because the anjumans will not take on moneyed males, only poor women. They don’t like female empowerment through micro-credit, and so use the bogus rhetoric of Islamic finance to promote their gender agenda.

Can you imagine these pillocks? How on earth can they justify this kind of loser behaviour? Interest in loans is not un-Islamic, you idiots. If you think that’s wrong, go check out what happens in Saudi Arabia, they merrily lend away on interest. And if you think that they are wrong, why do you suck up to them starting from Hyderabad Airport to their hotel rooms? Sheesh.

Thursday, February 7

Unease voiced over Islamic bonds

The FT has now picked this up that the Islamic bonds called as Sukuk are not really Islamic. But that's an oxymoron, anybody who seens the return on these bonds and compares them to the yieldcurve, does a correlation will simply see that its just interest based, just not called as interest.

Very worrisome, some form of equity participation has to be built into these structures otherwise this entire market will collapse. Also see the commentary around the standardisation problem. Remember that if they standardise the definitions of riba and Islamic Finance globally, then they have standardised, for the first time across the board, a single view of what one part of Islam theology says. That, in turn, will really be interesting.

All this to be taken with a grain of piquant salt!!!

Tuesday, January 29

Further debates on the Shia view on Islamic Finance

Further to my previous note, there are two additional posts which are worthwhile reading.

1. A comment on the original article. I quote: I share Hamoudi’s criticism of the gimmickry that the modern-day practice of Islamic finance seems to relish.......I am not impressed by the gimmickry, and I join Mahmud al-Gamal and Haider Ala Hamoudi in their skepticism towards what Hamoudi rightly calls ‘hypocrisy.’ From a system which is informed by the moral unease in Islamic law toward speculative investment which is not underscored by labour, the current Islamic banks have engaged into a spate of dubious transactions with Arabic names that all but dupe the customer. Commercial contracts between investor and worker under the classic mudaraba, which had been already thoroughly examined by Abraham Udovitch (Partnership and Profit in Medieval Islam, Princeton 1970) are replaced with murabaha and tawarruq schemes that mean little other than contorted, allegedly Islamised schemes, which are in fact poor replicas of Western banking. This is unfortunate, and has been rightly exposed in the better literature which Hamoudi, Gamal and Ibrahim Warde represent.

2. A followup comment. I further quote:

Professor Mallat and I agree entirely on the substance of Islamic finance, and he is certainly right that Sadr’s approach is quite interesting and indicative of his functional style. If, Sadr wonders, the bank is using the capital of one group of people to fund another, why not simply consider transactions across the financial intermediary to be one collective whole, disregarding as a result the formal existence of the intermediary? While that particular idea may not be attractive, the approach, of seeking to attach an Islamic substance to a shar’ia form, is more satisfying than the deceptive nonsense that dominates the practice of Islamic finance, as Professor Mallat properly points out.

I am afraid the general consensus is not looking good at all. But this universal bank proposal by Sadr is definitely worth considering.

Technorati Tags:

One Shia jurist's view of Islamic Finance

A fascinating exposition on how Muhammad Baqir al-Sadr, an Iraqi Shia Islamic Jurist who was incidentally killed by Saddam Hussein in 1980. Be that as it may, this article is worthwhile reading for people who are interested in how Sadr saw the world in terms of Shia theology.

Also check the footnotes, very very useful references for those who want to delve deeper into this rather unexplored view of Islamic Finance (as it is heavily biased towards the Sunni and that too a twin polar world, one the Arab world and second is the Malaysian World). And believe you me, there is a difference between the Shia and Sunni thought as this paper shows.

For example, Sadr indicates that Islamic economics is intended to serve three objectives: to ensure multiple ownership forms of property, to put in place limited economic freedom for commercial actors, and to achieve social justice in commercial affairs. This kind of formulation is very very different from the Sunni thought where the first two objectives are not formulated as such. The third is, for example, the deep theological and religious thought given to the proper and fair functioning of physical markets.

Mind you, this limitation of economic behaviour, such as what we recognise as regulation in the western world, is quite curious and interesting and ties directly into what we would see as the presence of theocrats who guide the great ship of the state.

An interesting aside is about wages. Should a worker receive a wage or a share of profit? Classically speaking, a worker should receive a share of profit rather than a wage as a wage is being fixed and putting a price on labour. So it is a type of interest after all as the wage is not variable. So Sadr goes through some rather torturous theological explanations to get by this problem.

But that is not a problem because in Shia Islam, you have the deputy of the Hidden Imam, the great company of Ayatollah's, who can decipher and decode and denote and devolve and take care of interpreting this complicated matter. Mind you, with the current cries for standardisation and formation of IF Councils and standard's bodies, has anybody noticed that the structure of Islamic Finance is slowly starting to resemble what we see in Iran? As in having Theologians sitting on standards and expert bodies to judge on the suitability of instruments, actions etc. Quite a curious thing and something that not very many people have identified. The fact that this is seriously against Sunni theology (nobody to intercede between a man and Allah) is besides the point.

The author unfortunately damns the current Sunni practice rather badly, and I quote: Given the substantial difficulty of maintaining a financial institution that neither took interest on commercial loans nor engaged in the types of commercial uncertainty banned by the doctrine of gharar, Islamic financial institutions have fallen back upon stratagem and artifice in order to function

The author points to countries like Malaysia where you have both conventional and Islamic finance systems running where evaluation can take place, but unfortunately, as I pointed out earlier, it has rather failed miserably. I have a quibble over the author's proposal for a universal Islamic bank, because he does not explain how exactly the risk transfer would happen. But still, the epistemological framework of Sadr is quite interesting indeed and could well be a model for others to follow, if they can get over the theological hump, that is.

All this to be taken with a grain of piquant salt!!!

Saturday, January 26

Islamic Finance and Credit Rating

For what it is worth, I agree with this. Credit Rating agencies have to take into account all material information while rating bonds. So why on earth can they say that they are rating everything except for whether they are sharia compliant or not? Well, if somebody withdraws the sharia fatwa, then the bondholders are sunk, so this evaluation by the credit rating agencies is crucial! If nothing else, it will force standardisation on the market and make the credit rating transparent.

Technorati Tags:

Sunday, January 20

Islamic Banking Paper

Here's a free working copy of the paper referred here which is causing all the fuss.

Technorati Tags:

Only a negligible bit of Islamic bank financing in Malaysia is strictly Islamic

Now here's a surprise, these two academics in a recent paper have determined that only 0.5% of Islamic Bank financing on the asset side is based upon true Islamic finance principles. On the liability side, the situation is different and has true Islamic deposit which account for 70% of the overall deposit base. In other words, if I understood this correctly, the depositors are doing well according to the Islamic Finance theory, but the lending side is not.

But the situation is a bit different when they dig into the deposits side. The authors further determine that the rates on the mudarabah deposits is lower than conventional rates and very closely follows the conventional rates (but not vice versa). In other words, to determine the mudarabah deposit rate, take the conventional interest rate, subtract a discount and offer to customers. I quote from their conclusions:

First, unlike conventional banking, PLS financing encounters severe principal–agent problems. Moral hazard problems associated with ex-post information asymmetry, for example, are especially significant in PLS financing because the entrepreneur (borrower) has incentive to under-declare or artificially reduce reported profit.

Also, in the case of mudarabah (profit-sharing) contracting, the entrepreneur has an incentive to undertake high-risk projects because the entrepreneur is actually given a call option whereby he or she gains on the upside but bears no losses at all on the downside. PLS financing, thus, requires more costly monitoring.

Second, the adoption of PLS financing is disadvantaged by a lack of management and control rights.

Finally, our study suggests that the adoption of the PLS paradigm is constrained by competition as well as by best practices from conventional banking. Religion notwithstanding, individuals can choose to bank with an Islamic bank and/or a conventional bank. Thus, in terms of best practices, Islamic banking practices often cannot deviate substantially from those of conventional banking because of competition. In particular, our study shows that the returns on the Islamic deposit accounts are effectively pegged to the returns on conventional banking deposits because of competitive reasons.

I concur with the two conclusions, but that is no different from any other venture, initial, angel, initial feedstock, project or any other kind of entrepreneur or corporate funding. In other words, you will hit these problems anyway irrespective of what kind of banking system that you run. If you remove conventional banking, then the third problem goes away (ostensibly!).

So even if you remove conventional banking from your country, you will still have an (implied) interest rate because other countries have conventional banking systems, and you have a currency exchange rate. So I can determine what an implied interest rate would be. Only way around this problem would be to convert the entire world's financial system to Islamic Banking.

But that still does not remove the problem of actually determining the proper rate of return in the absence of an interest rate. While large projects can have that kind of Private Equity or investments structure, for smaller sums, it is simply not effective or efficient for you to determine a suitable rate of return. Each transaction will take so long that you will become constrained very soon. In other words, if you have to do a full analysis every time anybody wants a mortgage, overdraft, working capital loan or what have you, the banking system will soon come to a grinding halt. On the other hand, you simply cannot expect every depositor to understand how the bank is performing to really evaluate the profit contribution of deposits kept in the bank.

Very interesting indeed. If Malaysia, which has the arguably most advanced Islamic Banking Market is showing these signs, then well, there is much further to go before the market is developed and settled down, avoiding problems like this.

Here's the paper in question:

Beng Soon Chong and Ming-Hua Liu, Islamic Banking: Interest-Free or Interest-Based, Pacific-Basin Finance Journal In Press, Abstract: A unique feature of Islamic banking, in theory, is its profit-and-loss sharing (PLS) paradigm. In practice, however, we find that Islamic banking is not very different from conventional banking. Our study on Malaysia shows that only a negligible portion of Islamic bank financing is strictly PLS based and that Islamic deposits are not interest-free, but are closely pegged to conventional deposits. Our findings suggest that the rapid growth in Islamic banking is largely driven by the Islamic resurgence worldwide rather than by the advantages of the PLS paradigm and that Islamic banks should be subject to regulations similar to those of their western counterparts.

Technorati Tags: ,

Thursday, January 17

As Islamic banking takes off, new courses are being set up in the universities

Good Stuff. I quote:

It’s the fastest-growing sector of the banking industry, yet few City boys know much about it and hardly any finance students are being taught it. But Islamic banking’s mysteries are now beginning to be unveiled and just this last month a business school and an accountancy body have announced new postgraduate programmes specialising in it.

Teaching the complexities of the markets and the Byzantine mass of Islamic scripture is impossible in a year, so Bangor’s course will balance finance and Islam, with the emphasis on the first. “You have people who take the religious approach, where a lot of the debate is about the semantics,” says Phil Molyneux, professor of banking and finance and head of Bangor Business School. “We won’t be spending a lot of time on that.”

The new course has already attracted applications and interest from the Muslim world and even from non-Islamic financial hubs such as Hong Kong. Still, it is a fairly daring move. Most students are expected to come from overseas and the university faces stiff, and cheaper, competition from courses elsewhere, in particular the International Islamic University Malaysia.

Is one module enough? “We are not saying that a course is enough, but a Masters is too much,” says Dr Marwan Izzeldin, course tutor at Lancaster. “A Masters will limit their chances. There are still more jobs in traditional banking than in Islamic banks.” The course will be sufficient, he says, for graduates to work in the sector, analysing Islamic financial products.

All this to be taken with a grain of piquant salt!!!

Monday, January 14

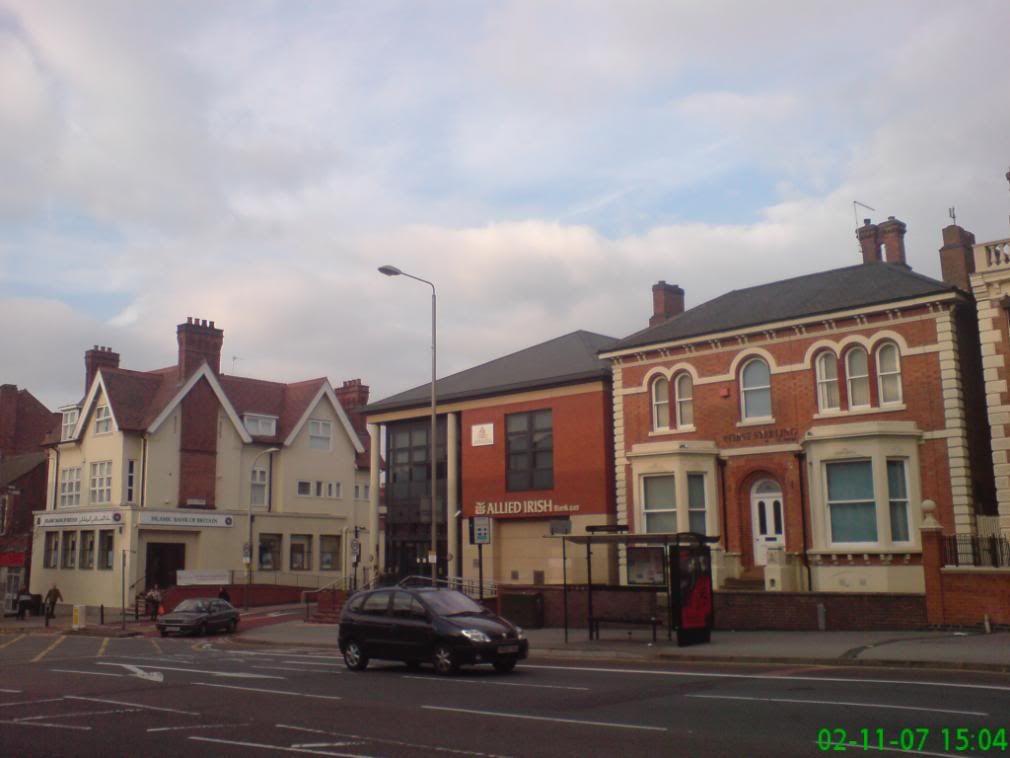
Islamic Banking on the UK High Street!

Some people are still not sure about the prevalence of Islamic Banking in the west. Well, here's a photo I took of the high street at Leicester. See the far left hand side building? That's Islamic Bank of Britain.


Sunday, January 13

Disappointing coverage of technology and Islamic Finance

I was first exposed to the challenges that modern technical formulations of financial engineering face when they look at Islamic finance in the eye. This was almost 15 years ago when somebody asked me to remove the word interest from all screens of my interest rate swap trading  application. I just gibbered at him.

For example, any trader worth his salt will have a yield curve in his spreadsheet or application. Now, what I would be interested in (no pun intended), would be to find how on earth can you create, price and risk manage a Islamic finance instrument in a technical application without taking recourse to a yield curve (which in turn relies fully on "interest"). But this article does not say so. Bit disappointing, that!

Technorati Tags:

Friday, January 11

Islamic Insurance now!

How fascinating, this promises to be even better to keep track of! I am not very sure how this link to insurance will work but will investigate further.

Lloyd’s chairman Lord Levene has today spoken of the group’s desire to enter the Islamic insurance market, which provides insurance services that comply with the strict financial prohibitions laid out in the Muslim Shariah law that prevent betting or gambling on future outcomes.
Expressing his interest today with Bloomberg, Lord Levene suggested that the market for Islamic insurance was growing rapidly and was one of the key areas for expansion of the industry in the coming ten years, particularly as services become more widespread and more developed by Western insurance groups.
Amongst the firms already offering Islamic insurance are Swiss Re, Allianz and AIG, who all have their own range of products that comply with the requirements of the Islamic faith.
A proportion of the Muslim faith believe that traditional insurance contravenes Shariah law, which forbids certain cornerstones of Western financial practice like interest payments, and specifically the perceived ‘gambling’ element of insurance that relies on certain future outcomes.
As a result the demand for Islamic insurance is increasing, which would offer a faith-sensitive alternative to traditional insurance to ensure there are no ‘holes’ left by a lack of cover derived from religious points of view.
It remains to be seen whether Lloyd’s move into the market will prove to be successful commerically, following steps by a number of other insurers to already offer Islamic financing and insurance, which is seen as a hotspot for future development of the industry on a global scale.
With just 1% of the world insurance market coming from the Middle East, it is possible that the introduction of more widespread alternatives to Western insurance could open a massive and lucrative hidden market for cover in the Eastern regions and in some emerging economies.

All this to be taken with a grain of piquant salt!!!

More links on Risk Management in Islamic Finance

Risk Management:

1. Growth in Islamic Finance Spurs Need for New Risk Management Methodologies

Two globally recognizedorganizations have teamed up to take on this challenge -- the GlobalAssociation of Risk Professionals (GARP: www.garp.org) and the Banque du Liban(www.bdl.gov.lb). They will jointly develop a first-of-its-kind Certificatein Risk Management for Islamic Financial Institutions due to be launched inlate 2008.
The expertise on Islamic finance from the Banque du Liban combined withGARP's proficiency in creating globally accepted standards on risk managementmethodologies, such as their globally recognized FRM program, will result in abenchmark approach to assessing risk around Sharia'a-compliant financialproducts. "There will be much input from experts around the world to make surewe get this right," said Chris Donohue, PhD, Head of GARP's Research Center."We will have a Technical Committee that will work on developing the contentfor the Certificate and an Advisory Group comprised of Islamic banking andderivative product experts to give us feedback throughout the process." The Advisory Committee will be co-chaired by Dr. Ahmed Jachi, ViceGovernor of Banque du Liban and Dr. Anthony Saunders, Professor of Finance atNew York University's Leonard Stern School of Business.

2. Book on financial risk management and Islamic Finance:

Risk management for Islamic banking financial products and services is one of the greatest challenges that many westernized, as well as Islamic Banks, are facing today.As a result of this market growth in Islamic financial products there is a high demand to understand how to assess and manage the risks arising from applying these products and services. Credit, operational, market and liquidity risks together with the risk of non compliance with the Shariah law are becoming very hot issues for financial institutions. This book presents a common framework of how to efficiently manage the risks faced and minimise the overall degree of Islamic financial risks. This book is a valuable guide for those working in both non-Islamic and Islamic finance.

Contents Principles of Islamic FinanceRisk Management Issues in Islamic Financial ContractsBasel II & IFSB for Islamic Financial RiskMarket Risk in Islamic FinanceCredit Risk in Islamic FinanceOperational Risk in Islamic FinanceConcluding Remarks

All this to be taken with a grain of piquant salt!!!

Islamic Finance, an email which I wrote:

I was discussing with somebody on the internet and this is what I wrote to them.


Think about it, the accountants and financial training institutions are coming up with courses which are open to all so that they can do what these mullah's are doing. I estimate that there are about 100 odd experts in this field, and they are paid millions. When this is the situation, and their performance is not consistent, then the market will fix this problem. Hence you can very well end up having a degree like CFA Islamic Finance. And then anybody and his dog can get this degree and be qualified to determine what is islamic and what isnt. So their power will go slowly. Not vanish, but it will diffuse to a point where hopefully sanity reins.

Second, it will be regulated by regulators who dont give a toss about how you invest, but the only thing that they care about is consumer protection. So its their wild and wooly ideas which have to modify to satisfy this test, not the other way around as is till now. In other words, up till now, its like this. I am Shiekh....., i SAY this is right on a Sharia basis. Live with it. End of story. But now, you cant say that, at least, here in the UK. If you say that, then the FSA asks, ok, prove that your financial instrument is safe for BRITISH consumers. And that's why it took such a long time for the Islamic Bank of Britian to get its licence, but people are learning, I belive there are 4 now and more different kinds of institutions coming up simply because of the certainty this kind of regulatory regime provides.

Third is the risk management side. Again, there is a very big push to provide risk management aspects which cater for islamic banking, starting from PRMIA ro GARP to books by Palgrave MacMillian, etc. etc. For crying out loud, we even have awards for best islamic banking software provider!!!!. This again shows that the market has incorporated this different measure of investmenting and will standardise it. Again, the obscurantists will lose out.

Early days yet, but we are currently going through what I call as the 2nd stages of the gartner hype cycle, namely the Peak of Inflated Expectations! :)

but i reiterate, it is my firm believe that if somebody wants to invest according to his / her own faith, we should not stop that. :)

cheers

bd


All this to be taken with a grain of piquant salt!!!

Tuesday, January 8

Two Islamic Finance Consultation Documents Launched

The Islamic Financial Services Board has launched two documents for consultation, namely on
Capital Adequacy Requirements for Sukuk Securitisations and Real Estate Investment Guiding Principles on Governance for Islamic Collective Investment Schemes. Both are interesting topics. The first talks about better capital and risk management when exposed to Sukuk's (also connected to the Basel II debate, which is a different argument and debate altogether!) and the second one is more about the REIT structures within Islamic Finance.

Do read and reflect. I quote the press release

The ED of Capital Adequacy Requirements for Suk«k Securitisations and Real Estate Investment deals with aspects of regulatory capital requirements for institutions offering Islamic financial services (IIFS) in respect of Suk«k that are not covered in IFSB-1. These include:
capital requirements for IIFS that are holders of Suk«k; and
capital treatment of the exposures of an IIFS where it is, or acts in a capacity such that it is considered to be, the originator of a Suk«k issue, or as an issuer or servicer of a Suk«k issuance.
In respect to real estate investment, the ED deals primarily with:
capital requirements for an IIFS that invests its own funds in real estate investment activities; and
capital treatment of exposures in real estate investment activities where an IIFS either commingles the funds of investment account holders with those of shareholders (and other non-profit-sharing investment account holders) or otherwise invests the funds of unrestricted investment account holders.
The ED of Guiding Principles on Governance for Islamic Collective Investment Schemes aims to complement IFSB-3 and other internationally recognized governance standards, by reinforcing international best practices while addressing the specificities in the governance of Islamic Collective Investment Schemes (ICIS).
The contents of the ED are divided into four parts:
Part I relates to the approach to general governance, whereby the adoption of good governance practices as prescribed in other internationally recognised governance standards is reinforced;
Part II addresses transparency and disclosure and aims to improve the information environment for ICIS investors as well as to build on, amongst other things, the disclosure requirements recommended under the IFSB Disclosures to Promote Transparency and Market Discipline for Institutions Offering Islamic Financial Services (Excluding Islamic Insurance (Takaful) Institutions and Islamic Mutual Funds);
Part III focuses on compliance with Shari'ah rules and principles and addresses various specificities of ICIS that include (a) the process of portfolio screening by ICIS Operators; (b) the role of Shari'ah scholars in monitoring consistent compliance with the Shari'ah; and (c) the process of purification of tainted income; and
Part IV examines additional protection for ICIS investors and highlights the issues of adequacy of representation for investors in the organs of governance of ICIS as well as some prevalent practices (identified from an IFSB survey) that require appropriate oversight
.


All this to be taken with a grain of piquant salt!!!